How to Justify Software Expense to CFO: Build a Finance-Ready Business Case
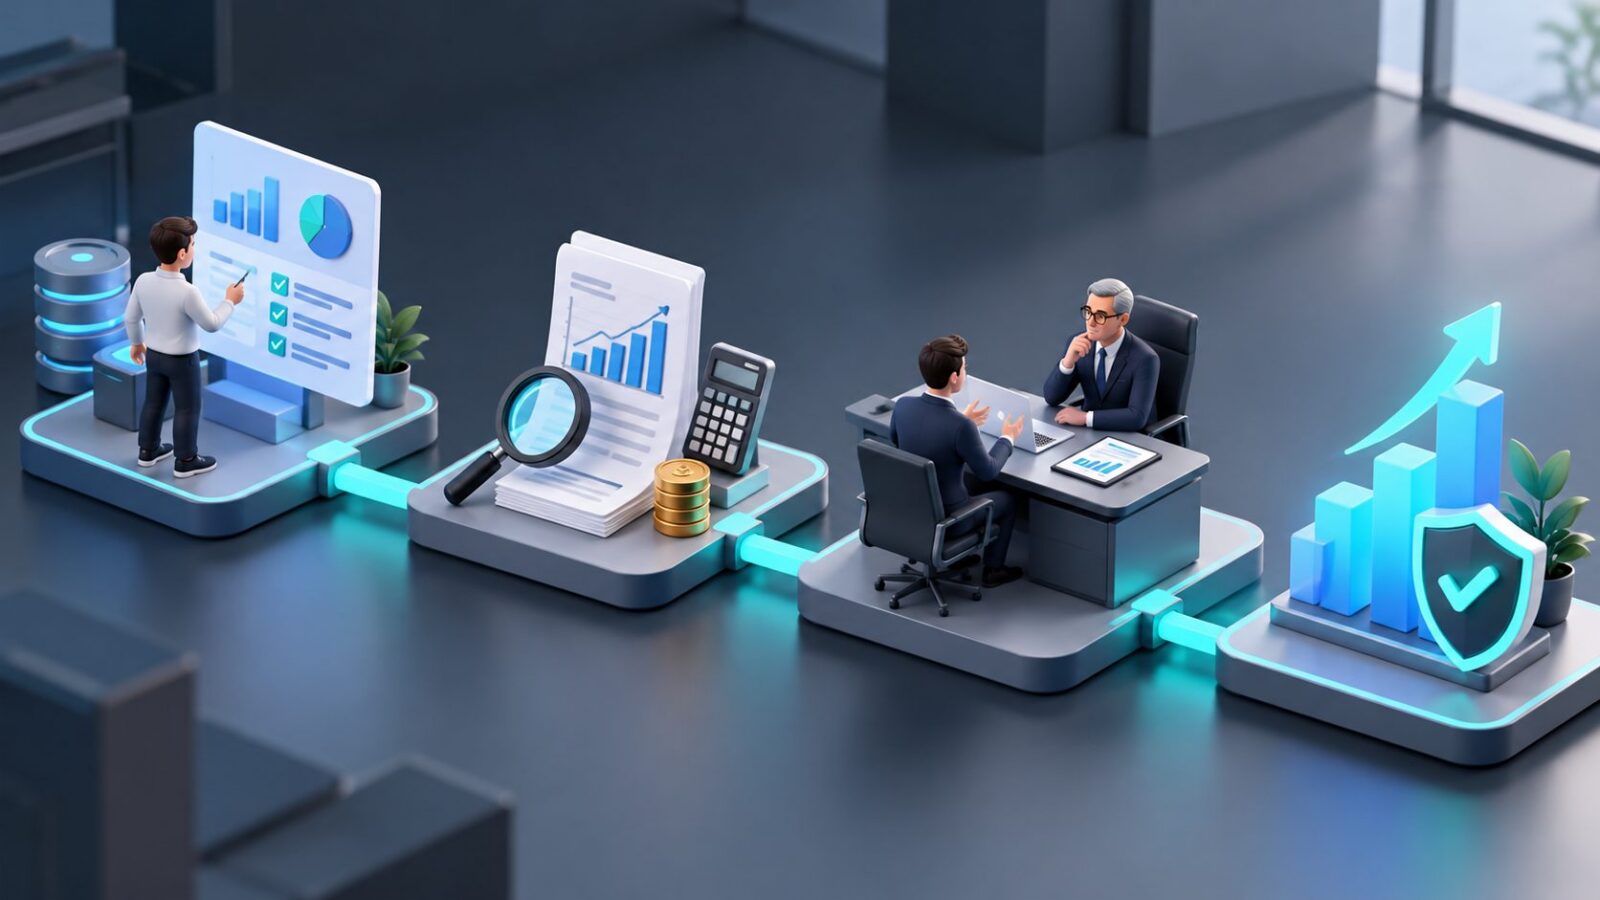
To justify software expense to CFO leadership, present it as an investment decision—not a feature request. Show the fully loaded cost, measurable business outcomes, payback period, risks, alternatives, and an accountable owner for results.
A CFO usually does not need another product demo. They need confidence that the proposed software deserves capital compared with hiring, process improvement, doing nothing, or renewing an existing tool. The strongest business case translates operational pain into financial impact.
What does a CFO need to see before approving software?
A CFO needs a concise model that connects the software to company priorities, cash impact, measurable benefits, and downside protection. The proposal should answer five questions:
- What problem is costing the business money today?
- What will the software cost over its full contract life?
- Which financial or operational outcomes will change?
- When will the investment pay for itself?
- What happens if adoption, savings, or revenue targets are missed?
This approach reflects common software business-case guidance: quantify benefits, estimate total cost of ownership, and align the proposal with executive priorities rather than leading with product capabilities. (arenasolutions.com)
Start with the cost of the current state
The most persuasive software justification often begins with the cost of not changing. Document the current workflow before discussing the vendor.
Measure:
- Hours spent on repetitive or manual work
- Rework, errors, and approval delays
- External agency or consulting costs
- Revenue delayed by slow execution
- Existing tools that could be retired
- Compliance, security, or business-continuity exposure
- Employee capacity consumed by low-value tasks
Avoid claiming that every hour saved becomes a payroll reduction. CFOs know that productivity is not automatically a headcount reduction. Instead, classify the benefit as one of three types:
| Benefit type | How to model it |
|---|---|
| Hard savings | A committed reduction in vendor, labor, or operating cost |
| Capacity released | Hours redirected to revenue, service, or strategic work |
| Risk reduction | Lower expected loss from errors, outages, noncompliance, or weak controls |
This distinction makes the proposal more credible because it separates cash savings from operational value.
Calculate total cost of ownership, not just the subscription
The annual license is only one part of the financial commitment. A CFO-ready proposal should include implementation, integration, training, administration, support, security review, data migration, renewal increases, and exit costs.
Use this formula:
Three-year TCO = subscription fees + implementation + integration + internal labor + training + support + expected renewal increase + exit or migration cost
For usage-based or AI-enabled software, model both a base case and a high-usage case. A fixed annual estimate can be misleading when consumption changes with user activity.
A useful improvement is to show committed cost separately from variable cost:
- Committed platform or seat fees
- Minimum usage commitment
- Variable usage charges
- One-time setup costs
- Internal operating cost
- Optional modules or expansion
You can also compare direct purchase, reseller, and cloud marketplace routes using a software reseller versus direct purchase cost comparison before presenting the final number.
Build a simple ROI and payback model
A CFO does not need a complicated spreadsheet. They need assumptions that can be tested.
Use these core calculations:
Annual net benefit = annual financial benefit − annual operating cost
ROI = (total benefit − total cost) ÷ total cost
Payback period = upfront investment ÷ monthly net benefit
For example, suppose a software implementation costs $48,000 in the first year and $24,000 annually afterward. If the business expects $90,000 in validated annual benefit, the first-year net benefit is $18,000 and the ongoing annual net benefit is $66,000.
The proposal should not present only the optimistic case. Include three scenarios:
| Scenario | Benefit assumption | CFO question answered |
|---|---|---|
| Conservative | 50% of expected benefit | What if adoption is slow? |
| Base case | Most supportable estimate | What is the likely outcome? |
| Upside | Strong adoption and execution | What could the investment unlock? |
A practical rule is to make the base case depend on observable drivers such as transaction volume, processing time, conversion rate, error rate, or current vendor spend—not generic claims about “increased productivity.”
Connect software outcomes to CFO metrics
The same software can appear valuable or wasteful depending on how it is framed. Translate product outcomes into metrics already used in financial reviews.
Examples include:
- Gross margin: lower service delivery or processing cost
- Operating expense: eliminate duplicate tools or external services
- Revenue productivity: more qualified opportunities or transactions per employee
- Cash conversion: faster billing, collections, or approvals
- Forecast accuracy: fewer budget variances and better planning
- Risk-adjusted return: reduced probability or impact of operational loss
- Working capital: shorter cycle times and fewer blocked transactions
For growth software, avoid presenting pipeline as revenue. Show the conversion assumptions behind the forecast. For cost-saving software, distinguish between budget reduction and capacity that is redeployed.
This is where many proposals fail: they report activity metrics, such as logins or tasks completed, without proving that those activities changed a business result.
Add a risk-adjusted view of the investment
A CFO is evaluating uncertainty as much as potential return. Include the risks that could reduce value:
- Low user adoption
- Integration delays
- Data migration problems
- Vendor lock-in
- Contractual price increases
- Feature deprecation
- Weak security or audit controls
- Unclear ownership after implementation
Then attach a mitigation to each risk. For example:
| Risk | Mitigation |
|---|---|
| Low adoption | Define department-level usage targets and executive sponsorship |
| Renewal surprise | Negotiate price protections, notice periods, and true-down rights |
| Vendor dependency | Document export procedures and transition responsibilities |
| Unplanned usage cost | Set usage alerts, budgets, and approval thresholds |
| Security review delay | Complete technical and compliance assessment before signature |
For contract-specific protection, review guidance on enterprise SaaS true-down rights and software vendor price-indexing clauses. These terms can materially change the downside case even when the list price remains unchanged.
Use a “replace, reduce, or avoid” savings bridge
One original way to strengthen a software request is to create a savings bridge instead of listing benefits in isolation.
Start with the new annual expense, then show offsets:
- Cancelled or consolidated software
- Reduced external services
- Avoided hiring
- Reduced overtime
- Prevented revenue leakage
- Lower expected cost of errors or incidents
The final line should be:
Net new annual spend = proposed annual cost − credible offsets
This number is usually more useful to a CFO than the gross contract value. It also forces the requesting team to identify what will actually change after approval.
Do not count an offset unless someone owns it. If a tool will be retired, name the owner and cancellation date. If capacity will be redeployed, identify the workflow and target metric.
Present the proposal in one page
A finance-ready software request can follow this structure:
- Decision requested: approval amount, contract term, and start date
- Business problem: current cost, constraint, or risk
- Recommended solution: why this option fits the requirement
- Three-year TCO: fixed, variable, and internal costs
- Benefits: savings, capacity, revenue, and risk reduction
- ROI and payback: conservative, base, and upside cases
- Alternatives considered: do nothing, build, hire, or use an existing tool
- Controls: adoption milestones, budget limits, and renewal review
- Accountability: business owner, finance owner, and measurement cadence
A concise proposal is easier to challenge and easier to approve. For a reusable approval workflow, adapt a software purchase justification email template to the figures in your model.
Common questions about CFO software approval
Should software be presented as an expense or an investment?
Present both views. It is an expense in the budget, but the approval decision should be evaluated as an investment with costs, benefits, timing, and risk.
What if the ROI cannot be measured precisely?
Use a range and label the assumptions. Pair uncertain benefits with measurable leading indicators, such as adoption, cycle time, error rate, or completed transactions.
How long should the payback period be?
There is no universal threshold. Match the payback period to the contract term, risk level, implementation effort, and the company’s normal capital-allocation standards.
What if the software improves employee experience but does not reduce costs?
Connect employee experience to a measurable business mechanism, such as lower turnover, faster onboarding, fewer errors, or higher service capacity. Do not treat satisfaction alone as a guaranteed financial return.
How should renewal be handled?
Approval should include a renewal review date, usage thresholds, owner accountability, and a decision rule for expanding, renegotiating, reducing, or cancelling the software.
Final takeaway
The best way to justify software expense to CFO reviewers is to make the decision financially transparent. Show the current-state cost, full TCO, measurable outcomes, conservative assumptions, downside protections, and a clear owner for results.
A strong software business case does not promise certainty. It gives finance enough evidence to compare the purchase with competing uses of capital—and enough controls to intervene if the expected value does not appear.
Keep reading
Enterprise AI Contract Clauses for Proprietary Data Protection
Enterprise AI contract clauses for proprietary data protection should control training, retention, subprocessors, deletion, and model changes. Use this buyer guide to negotiate stronger terms.
Negotiate Commercial LLM Customer Data Usage Rights
Negotiate commercial LLM customer data usage rights with practical clauses for training opt-outs, retention, subprocessors, deletion, and audit rights. Use this buyer playbook to strengthen your next AI contract.
Software Reseller vs Direct Purchase Cost: A True Buyer Comparison
Compare software reseller vs direct purchase cost beyond the quote, including discounts, marketplace fees, support, contracts, and total procurement effort. Build a defensible buying model.